Article Summary Credit scoring and bureau executives said expanded data can improve risk assessment, especially for borrowers with thin files or nontraditional income.
They cautioned lenders to validate AI and alternative data within workflows, regulations and capital markets requirements.
Data priorities: lower cost or bigger credit box?
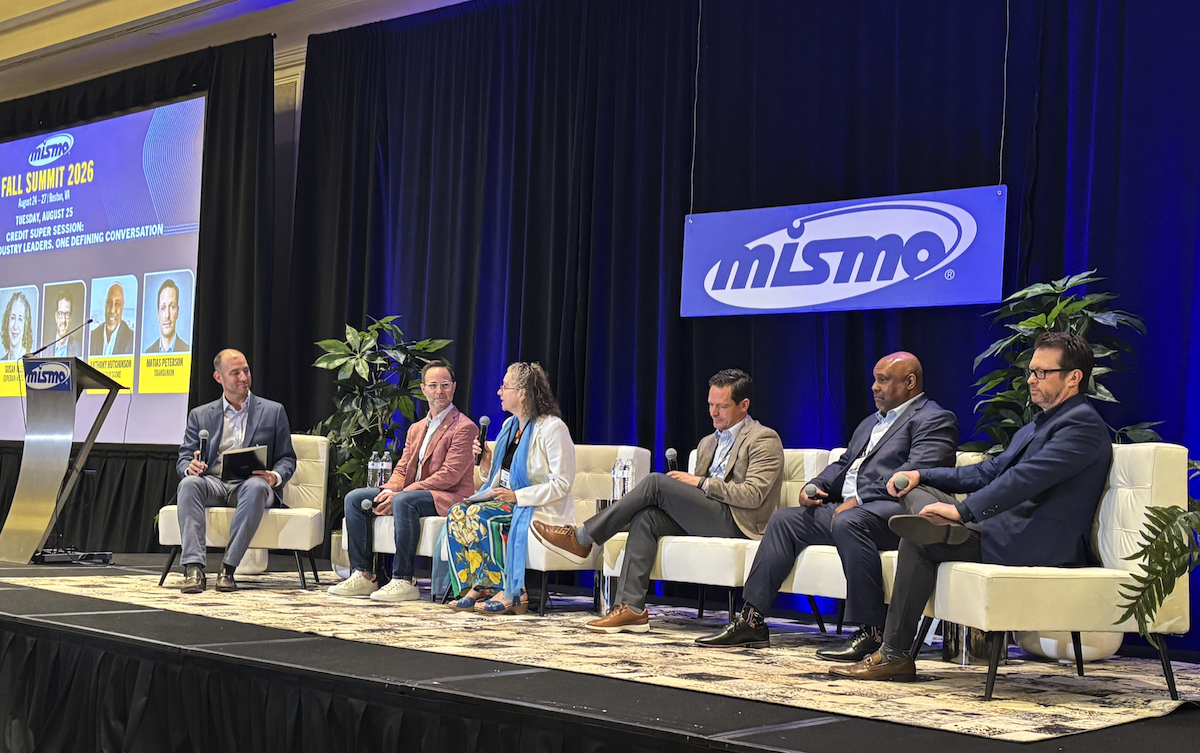
The question, Demola said, is how a lender designs its internal workflow around its priorities to reduce costs, qualify more borrowers or improve communications with consumers. At a moment when lenders remain under intense pressure to reduce the cost of originating a mortgage, bending that cost curve down is a nonnegotiable. Demola said that lenders consistently come to credit data providers with three objectives: “increasing revenue, reducing costs, increasing efficiency.” Still, as is often the case, cheaper does not necessarily mean better across the entire mortgage ecosystem. FICO’s Eric Lapin cautioned that scoring decisions do not end at origination; they extend through servicing, mortgage insurance and capital markets. A lower-cost option at the front end could create downstream pricing complications if investors or other market participants believe the risk is not factored in appropriately. He urged lenders to examine performance data and ensure investors, ratings agencies and mortgage insurers are aligned behind whatever models they adopt. That cost-versus-performance tension and the flexibility-versus-standardization dilemma are likely to escalate as an implementation issue as competition in mortgage credit scoring increases. Alternative data: a necessity and a challenge Alternative data raises a similar set of opportunity areas and challenges. Executives repeatedly pointed to rental payments, utility and telecommunications records, cash-flow information and consumer-permissioned banking data as ways to better evaluate consumers whose traditional credit files may not tell the full story. That applies especially to borrowers with thin files, self-employed income, gig work or other financial characteristics that do not check the same boxes as traditional W-2 underwriting patterns. Susan Allen, Experian’s chief product officer for housing, cautioned against describing that as simply “opening the credit box.” “There’s a big difference between accepting more risk as a way to approve more borrowers versus seeing risk differently, calculating it more effectively,” Allen said. A consumer with a thin traditional credit file “is not necessarily a consumer with a thin financial life,” she said, pointing to younger consumers using gig income, Venmo, buy-now-pay-later products and years of rental payment history. These evolving income and payment documentation trends may add up to the strongest business case for modernization. If lenders can identify additional qualified borrowers without adding materially more risk, new data streams can support both credit access and lender economics. TransUnion’s Matias Peterson noted that an increase of even 1 or 2 percentage points in approvals can significantly improve a lender’s results given the amount already invested in acquiring and processing mortgage prospects. AI’s devil in the details The panel agreed that the challenge lay in execution.More borrower information does not autonomously generate better underwriting. Lenders need systems that can ingest it, analytics that can test it and policies that govern when it should influence a decision.
Artificial intelligence adds another layer of analysis, provided that governance and reliability are validated. Panelists discussed AI applications in document processing, data extraction, analytics and consumer education, but Demola also raised the question of when an AI system could effectively begin “acting as a loan officer” and potentially trigger licensing requirements. Hutchinson highlighted evolving state and federal AI regulations, urging lenders to involve compliance and government relations teams when deploying new tools. The next phase of mortgage credit modernization, the panelists indicated, is no longer primarily about whether the industry can use more data. It can — and it’s anxious to do so. The competitive question now is where in their workflow ecosystems lenders should deploy it, and whether their systems, capital markets partners and compliance structures are prepared to turn more information into better decisions rather than adding more complexity.